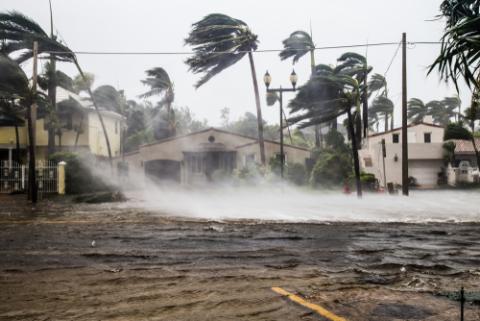
Hurricane Isaias is approaching the Gulf Coast, bringing the threat of damaging winds, heavy rainfall, storm surge, and flooding. For homeowners and businesses in the storm's path, protecting their families, employees, and property is the immediate priority. But once the storm passes, recovering from the damage can present another challenge: dealing with insurance companies.
Hurricane insurance claims can be complicated, particularly when insurers dispute the cause of damage, underestimate repair costs, delay payments, or deny coverage altogether.
At Morgan & Morgan, our hurricane insurance lawyers help homeowners, condominium owners, and businesses understand their coverage, navigate insurance disputes, and pursue the compensation they may be entitled to under their policies.
Common Types of Property Damage Caused by Hurricane Isaias
Hurricanes can cause extensive damage to residential and commercial properties, sometimes leaving property owners facing significant repair costs, temporary displacement, or interruptions to business operations. Depending on the circumstances and available insurance coverage, hurricane-related claims may involve:
- Roof and structural damage: Strong winds, flying debris, and falling trees can damage roofing systems, windows, walls, garages, and other structural components.
- Water damage: Wind-driven rain entering through storm-damaged roofs, windows, or other openings can cause extensive damage to ceilings, walls, flooring, and insulation.
- Flood damage: Rising water can damage a building and its contents. Flood damage generally requires separate flood insurance; secure a copy of your policy. Documents may be lost or damaged during the storm, and power or internet outages can make it difficult to obtain a copy from your carrier or agent—especially when many others are trying to reach them.
- Personal property losses: Furniture, electronics, appliances, clothing, equipment, inventory, and other belongings may be damaged or destroyed.
- Additional living expenses: Certain homeowners insurance policies may cover eligible temporary housing and related expenses when covered damage makes a home uninhabitable.
- Commercial property and business interruption: Businesses may experience damage to buildings, equipment, and inventory, along with certain income losses and additional expenses associated with covered interruptions.
Not all hurricane-related damage is automatically covered. Insurance policies may contain exclusions, deductibles, coverage limits, and other requirements that affect the benefits available.
What Should You Do if Hurricane Isaias Damages Your Property?
After a hurricane, your first priority should be making sure it's safe to return to your property. Downed power lines, floodwaters, unstable structures, and debris can remain dangerous even after the storm has passed. Once conditions are safe, consider taking the following steps to help protect your insurance claim:
- Document the damage. Take photographs and videos of affected areas and damaged belongings before beginning repairs whenever possible.
- Review your insurance policy. Familiarize yourself with your coverage, deductibles, exclusions, and claim reporting requirements.
- Notify your insurance company. Report the damage promptly and keep copies of your communications.
- Prevent additional damage. Take reasonable steps to protect your property from further losses when it is safe to do so, and retain receipts for emergency repairs.
- Keep important records. Save inspection reports, contractor estimates, photographs, receipts, and other documentation related to your claim.
You don't necessarily have to wait until your insurance company denies your claim to speak with an attorney. Morgan & Morgan may be able to help you understand your policy and available legal options at every step of the claims process.
Common Insurance Claim Disputes That May Arise After Hurricane Isaias
Even when property owners maintain insurance coverage, disagreements can arise over whether damage is covered and how much an insurance company should pay. Some of the most common hurricane insurance disputes involve:
- Wind versus flood damage: Insurers may argue that damage resulted from flooding or storm surge rather than wind or wind-driven rain. These distinctions can significantly affect coverage.
- Preexisting damage: An insurer may attribute damage to ordinary wear and tear, maintenance issues, or conditions that existed before the hurricane.
- Repair costs: Insurance estimates may differ from contractor assessments of the work necessary to repair or replace damaged property.
- Partial claim denials: An insurer may agree to cover certain losses while denying other portions of the same claim.
- Scope of damage: Disagreements may arise over how much of a roof, room, or other part of the property needs to be repaired or replaced.
- Supplemental claims: Additional damage discovered after an initial inspection or payment may require further documentation and a request for additional benefits.
These disagreements don't automatically mean an insurance company acted improperly. However, if your insurer's decision appears inconsistent with your policy or applicable law, an attorney may be able to help evaluate and challenge it.
How Morgan & Morgan Can Help With Hurricane Isaias Insurance Claims
Navigating an insurance dispute while recovering from a hurricane can be overwhelming, especially when you're facing costly repairs, temporary relocation, or business interruptions.
Morgan & Morgan's Insurance Recovery Group may be able to help by reviewing your insurance policy, evaluating the insurer's response, investigating disputed damage, and examining repair estimates and other supporting documentation.
When appropriate, our attorneys can also communicate with insurers, negotiate disputed claims, and pursue legal action to seek benefits available under your policy.
Whether your hurricane insurance claim has been denied, delayed, or underpaid, our team can help you understand your options and determine what steps may be appropriate.
If Hurricane Isaias damages your property, our team may be able to help before or after you file your insurance claim. Contact Morgan & Morgan for a free case evaluation to learn more about your legal options.
Frequently Asked Questions About Hurricane Isaias Insurance Claims
Does homeowners insurance cover flooding from Hurricane Isaias?
Standard homeowners insurance policies generally exclude flooding caused by rising water or storm surge, which may require separate flood insurance.
However, hurricanes can cause multiple types of damage, and coverage disputes may arise when both wind and water contribute to a loss. The applicable policy and circumstances of the damage determine what coverage may be available.
What if my Hurricane Isaias insurance claim is denied?
A denied claim doesn't necessarily mean you have no options. Your insurer may dispute the cause of damage, apply a policy exclusion, or argue that certain losses aren't covered.
An attorney can review the denial, examine your insurance policy, and determine whether there may be grounds to challenge the decision.
What if my insurance company doesn't offer enough to repair the damage?
If your insurance company's estimate doesn't reflect the extent of your covered damage or the reasonable cost of repairs, you may be able to challenge the amount offered.
Contractor estimates, inspection reports, photographs, and other documentation may help support your request for additional benefits.
How long do I have to file a Hurricane Isaias insurance claim?
Insurance claim deadlines depend on the state, the type of policy, and the circumstances of the loss. Certain states have specific deadlines for initial, reopened, or supplemental property damage claims.
It's generally best to report damage as soon as reasonably possible and review the requirements of your insurance policy. An attorney can help you understand which deadlines may apply to your situation.
Why should I choose Morgan & Morgan for my Hurricane Isaias insurance claim?
Hurricane insurance claims can involve complicated policies, competing damage estimates, questions about wind versus flood damage, and insurance companies working to limit their financial exposure. Our Hurricane Lawyers are experts in the field and can assist you at every step of the way.
As America's Largest Injury Law Firm™, with more than [ftp_global_var:attorney_count] lawyers nationwide, $[ftp_global_var:total_funds_recovered_count] billion recovered, and [ftp_global_var:years] years of experience, Morgan & Morgan has the resources to review disputed claims, investigate storm damage, and challenge insurance companies when legitimate claims are denied, delayed, or underpaid.
We believe everyone deserves access to excellent legal representation, regardless of their financial circumstances.
There is no cost to speak with us about your Hurricane Isaias insurance claim. Qualifying cases are handled on a contingency-fee basis, meaning there are no upfront attorney's fees and you pay nothing unless we win your case.
That's our promise: The Fee is Free® unless we win.
If Hurricane Isaias damages your home, business, or other property, contact Morgan & Morgan today for a free, no-obligation case evaluation. Our team can review your circumstances and help you understand your legal options.